Requesting a Chargeback on an Erste Bank Credit Card
Waking up to a mystery charge on your credit card statement is a universal expat nightmare that many expats encounter in Vienna. It’s a gut-punch that leaves you feeling vulnerable and frustrated, especially when you are still navigating the nuances of the local banking system. This guide solves that anxiety by providing the exact steps and local knowledge required to successfully initiate a chargeback with Erste Bank.
Understanding the Grounds for a Chargeback in Austria
In the Austrian banking landscape, a chargeback is officially referred to as a "Reklamation" or "Einspruch." While we often use the English term, you will see these German words throughout the George banking interface. It is important to realize that a chargeback is not a guaranteed "delete" button for any transaction you regret; it is a legal and contractual mechanism designed to protect you from specific failures in the payment chain. Before you start the process, you need to identify which category your problem falls into, as this dictates the evidence you will need to provide.
The most common reason is fraudulent activity. If you see a charge from a merchant you have never heard of, or if a transaction occurred in a city you haven't visited, this is a clear-cut case of fraud. I remember the first time I saw a random 400 Euro charge from a high-end boutique in Paris while I was sitting in a coffee house in Graz—it’s a terrifying moment, but Erste Bank's systems are generally quite robust at handling these if reported quickly. In such cases, the bank isn't just reversing a charge; they are likely going to cancel your card entirely and issue a new one to prevent further theft. This is a critical part of Money in Austria 2027: Banking, Payments, and Financial Setup where security and rapid response are paramount.
The second category involves commercial disputes. This is when you authorized the payment, but the merchant failed to hold up their end of the bargain. This could mean the item never arrived, the service was never rendered (such as a canceled flight where the airline refuses a refund), or the item received was significantly different from the description. For those of us who frequently order furniture online for a new apartment, this is a common headache. If you’ve dealt with Understanding Kaution (Deposit) and Provision (Commission) for a rental, you know how important every Euro is when setting up your new life. You must prove that you attempted to resolve the issue with the merchant first before the bank will even look at your claim.
The Role of First Contact with the Seller
In Austria, the burden of proof rests heavily on the consumer for commercial disputes. Erste Bank, like most major institutions such as those mentioned in Comparing Erste Bank, Raiffeisen, and Bank Austria, requires evidence that you tried to find an amicable solution. This means you need a paper trail. If you ordered a pair of shoes that never arrived, you cannot simply click "dispute" the next day. You must email the merchant, wait for a reasonable response time (usually 7 to 14 days), and keep copies of those emails.
If the merchant is ghosting you or providing "copy-paste" excuses without a refund, that is when your chargeback case becomes strong. Save your emails as PDF files. If the merchant promised a refund but it hasn't appeared on your statement after 15 days, that specific "promise of refund" email is the "golden ticket" for your chargeback application. It proves the merchant admits they owe you money, which makes the bank’s job much easier.
Fraudulent Transactions and Police Reports
If your chargeback is due to a stolen physical card or a compromised card number where you suspect criminal intent, the bank may ask for a "Verlustanzeige" (notice of loss) or a police report. While not always mandatory for small amounts, having a digital copy of a police report can significantly speed up the process for larger sums. In Austria, you can report theft at any "Polizeiinspektion." It feels intimidating if your German isn't perfect, but they are used to dealing with these administrative filings. This proactive step is often a requirement for various forms of Legal Protection Insurance (Rechtsschutzversicherung) Overview that many expats carry to protect themselves from financial disputes.
The Step-by-Step Process for Erste Bank Customers
The beauty of being with a modern bank in Austria is the "George" ecosystem. Erste Bank has invested heavily in making their digital platform one of the most user-friendly in Europe. Most chargebacks can now be initiated directly within the app or the web interface, which saves you from having to visit a branch in person and wait in line.
First, log into your George account on a desktop if possible, as the desktop version often provides a clearer view of document upload fields than the mobile app. Navigate to your credit card account—be careful not to confuse this with your standard current account, as the rules for Bankomatkarte (Debit) vs Credit Card Usage in Austria are slightly different. Once you are looking at your credit card transactions, find the specific line item that is causing the trouble.
Navigating the George Interface
Click on the transaction to open the "Transaction Details" view. You should see a button or a link labeled "Umsatz reklamieren" (Dispute transaction) or sometimes located under the "Functions" menu. When you click this, George will walk you through a digital wizard. It will ask you the reason for the dispute. Be very precise here. If you select "Fraud," the system will likely trigger an immediate block on your card. If you select "Service not rendered," it will prompt you for more information about your interaction with the merchant.
During this process, you will reach a screen where you can upload attachments. This is where your PDFs of emails, invoices, and shipping confirmations go. Do not skip this step. An empty chargeback request is almost always rejected or delayed by several weeks. If you are unsure about your card's specific terms or if you are eligible for certain protections, it’s worth reviewing Opening an Austrian Bank Account: Requirements and Top Banks to see how Erste compares to others in terms of consumer protection.
Using the s-ServiceCenter and Paper Forms
If for some reason the digital "Reklamation" button isn't appearing—which sometimes happens with very recent transactions that are still in "Pending" (Provisorisch) status—you will need to use the s-ServiceCenter. You can find this in the side menu of George. Here, you can send a secure message directly to the credit card department. In your message, include the date, the merchant name, the exact amount, and the last four digits of your card number.
In rare cases, particularly for specialized cards like the Platinum card or co-branded cards, you might be redirected to a third-party portal like "Card Complete" or "AirPlus." If Erste Bank is just the distributor and not the actual processor, you will have to fill out a PDF form and email it to the processor's dispute department. Even then, you can usually find these forms within the George help section. Make sure to check Bank Fees: Understanding Account Maintenance and ATM Charges to ensure that your specific card tier doesn't have unique fees associated with "unjustified" chargeback requests, though most standard disputes are free to file.
| Dispute Type | Required Evidence | Recommended Action Timeline |
|---|---|---|
| Unauthorized Fraud | None (Card should be blocked) | Immediately upon discovery |
| Non-Delivery of Goods | Correspondence with seller, Order confirmation | 15–30 days after expected delivery |
| Defective Merchandise | Photos of defect, Return shipping receipt | Within 14 days of receiving item |
| Duplicate Charge | Screenshot showing two identical charges | As soon as both charges are "Posted" |
| Canceled Service | Cancellation confirmation from merchant | 15 days after refund was promised |
What Happens After You Submit: Timelines and Expectations
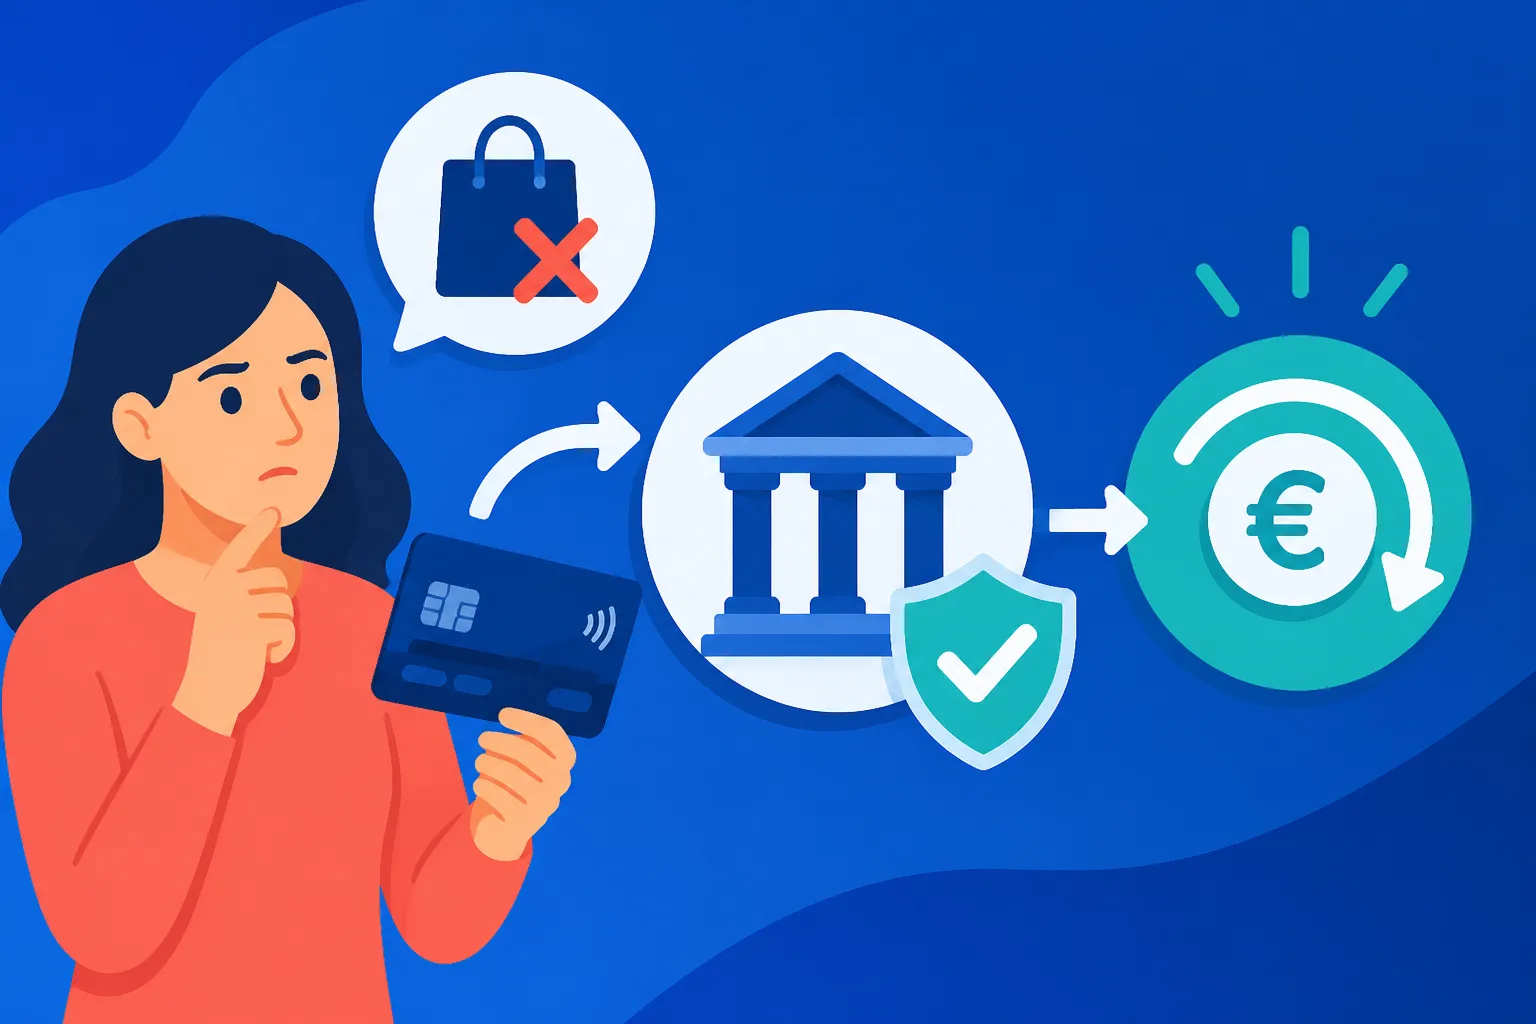
Once you hit "Submit," the process moves out of your hands and into the complex world of interbank communication. This is where patience becomes a virtue. Unlike a bank transfer which happens in seconds, a chargeback can take anywhere from a few weeks to several months. This is because the bank must follow the strict rules set by Visa or Mastercard.
Erste Bank will first review your claim internally. If it looks valid, they will "charge back" the money from the merchant's bank. You might see a temporary credit appear on your account within a few days. However, do not spend this money immediately! This is often a "provisional credit." The merchant has a right to respond. They usually have 30 to 45 days to provide evidence that the charge was legitimate (e.g., a signed delivery receipt). If the merchant wins the dispute, the bank will take the money back out of your account.
The Interbank Process: Mastercard and Visa Rules
Mastercard and Visa have massive rulebooks that govern these disputes. They provide specific "Reason Codes" for every chargeback. When Erste Bank submits your claim, they assign it one of these codes. For example, Code 4855 for Mastercard relates to "Goods or Services Not Provided." This standardized system is why having the correct documentation is so vital. If your documentation doesn't perfectly match the requirements of the code, the merchant’s bank will automatically reject it.
For many expats, this technicality is where things go wrong. If you’ve recently moved and are still waiting for your Applying for Credit Cards in Austria: Approval Odds to be finalized for a second card, you might feel the pressure of having these funds tied up. This is why it is wise to have a small emergency fund in a separate account so a single disputed charge doesn't ruin your monthly budget.
Potential Rejection and the Ombudsman Option
If your chargeback is rejected and you still believe you are in the right, don't give up. Erste Bank will usually provide a reason for the rejection. Sometimes it’s as simple as "the merchant provided a tracking number that shows delivered." If you can prove that the signature on that tracking number isn't yours, you can sometimes appeal.
If you reach a total stalemate with the bank, you can turn to the "Gemeinsame Schlichtungsstelle der Österreichischen Kreditwirtschaft" (the Austrian Banking Ombudsman). This is a free mediation service that helps resolve disputes between banks and customers. They are an excellent resource for foreigners who feel they are being treated unfairly due to a lack of local systemic knowledge. It is also worth checking if your Household Insurance (Haushaltsversicherung) Explained or a specific travel insurance policy covers "purchase protection," which can act as a fallback if the chargeback process fails.
Tips for Avoiding Future Payment Disputes
While knowing how to fight a chargeback is essential, preventing the need for one is even better. As an expat in Austria, you are often targeted by "subscription traps" (Abofallen) or less-than-reputable online shops that look local but ship from abroad.
Always use "Mastercard Identity Check" or "Visa Secure" features. Within the George app, make sure you have "Push Tan" enabled. This ensures that almost every online purchase requires you to physically swipe or enter a code on your phone to authorize the transaction. This makes it almost impossible for a hacker to use your card without your phone, and it also serves as a "second thought" mechanism for you before committing to a purchase.
Security Habits and the George App
Regularly check your "Transaction List" in George. I make it a habit to look every Sunday evening. The faster you catch an error, the easier it is to fix. If you see a small "test" charge of 1 Euro or 0 Euro from an unknown source, block your card immediately. This is often a sign that your data was leaked, and the "big" charge is coming next.
Furthermore, consider the insurance products that come with your Erste Bank card. Many of the premium "Gold" or "Platinum" cards in Austria include built-in travel and purchase insurance. If a merchant refuses to refund a flight, it might actually be faster to file an insurance claim through the card's insurance partner than to go through the interbank chargeback process. This is a nuanced area of KSV1870 Credit Score: How It Affects Loans and Rentals as maintaining a clean financial record and high credit standing often involves utilizing these secondary protections effectively.
Disclaimer
This guide is provided for informational purposes only and does not constitute legal or financial advice. Banking regulations, Erste Bank's internal policies, and the terms of service for Visa and Mastercard can change. Always consult with a qualified professional or contact Erste Bank directly for the most current information regarding your specific financial situation.