Does Haushaltsversicherung Include Privathaftpflicht?
You’ve finally secured a flat in Vienna or Graz after weeks of hunting, only to have the landlord demand proof of insurance before handing over the keys. When I first moved to Austria, I was overwhelmed by the sudden pile of German paperwork and the fear that I was being upsold on unnecessary policies. This guide explains the crucial link between household and liability insurance so you don't overpay or leave yourself legally exposed.
The Bundle Reality: How Household and Liability Insurance Work Together
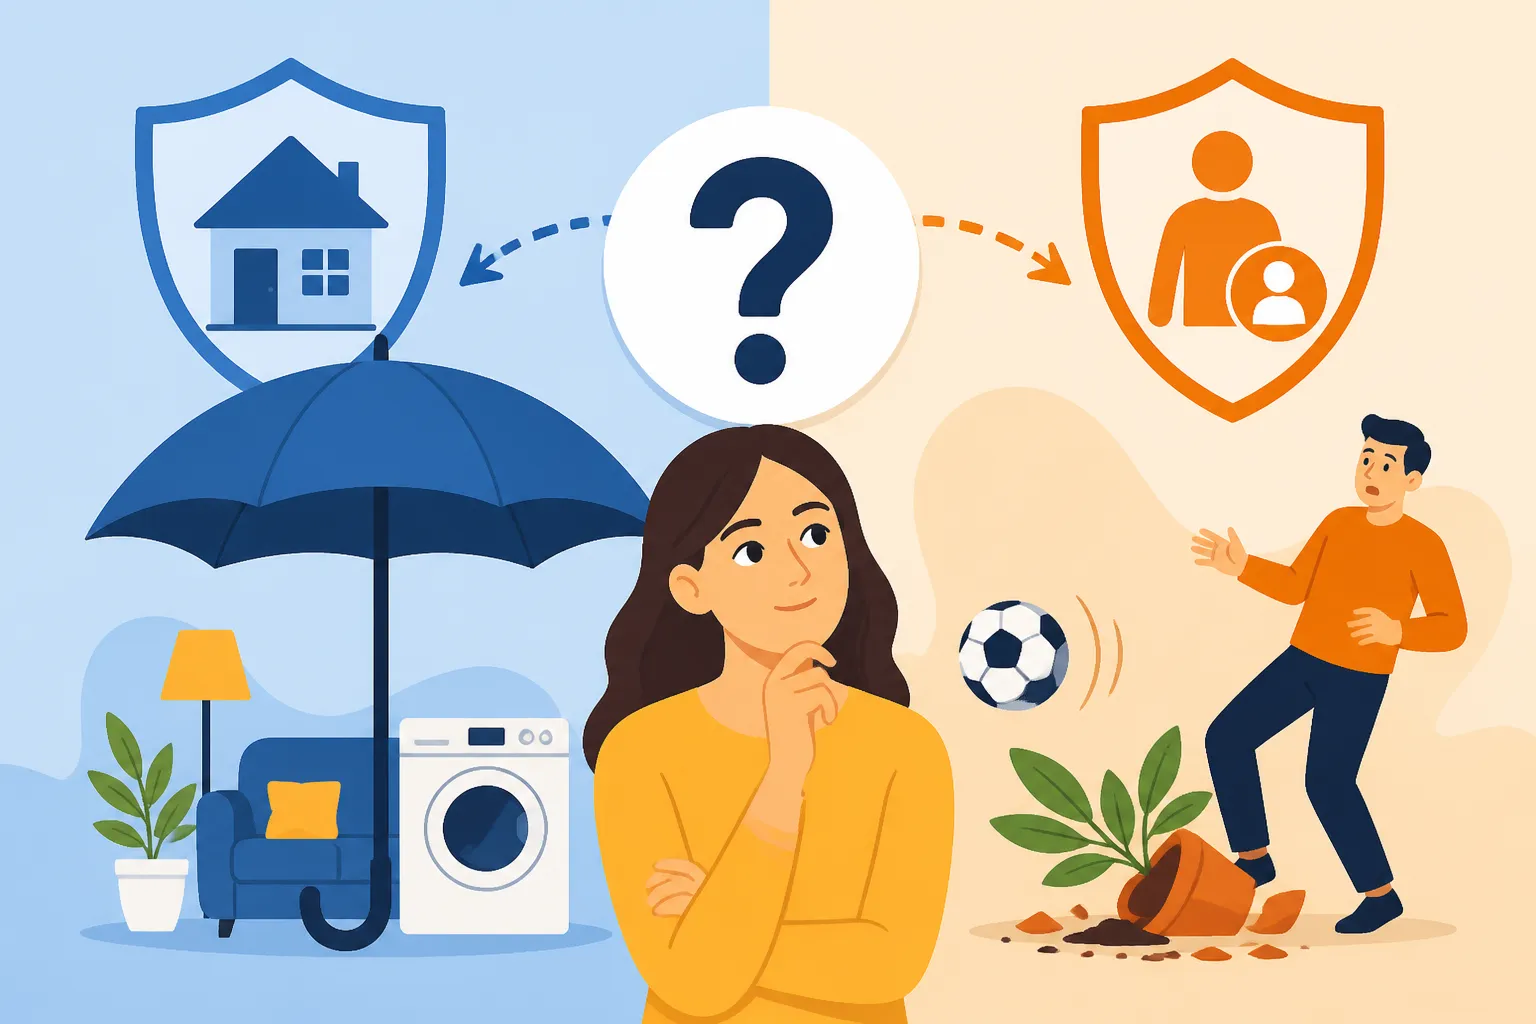
In many countries, you buy insurance for your stuff and insurance for your actions as two completely different products. Austria does things a bit differently. While they are technically two different types of coverage, in the Austrian insurance market, they are almost always sold as a single package. When you hear someone talking about their Haushaltsversicherung, they are usually referring to a policy that includes Privathaftpflicht as a standard component.
This bundling is a massive relief for expats because it simplifies the administrative burden. However, it also creates a lot of confusion. Many foreigners assume that "Household Insurance" only covers their physical belongings like their laptop, sofa, or clothes. If you only focus on the value of your furniture, you might choose a policy with the lowest possible premium, accidentally ignoring the much more important liability limits hidden in the fine print.
I learned this the hard way when I realized my initial policy had a very low liability cap that wouldn't have even covered a serious bike accident. Understanding that the Household Insurance (Haushaltsversicherung) Explained documents you receive from an agent are dual-purpose is the first step to navigating the Austrian system correctly. Most landlords will require this bundle because it protects the apartment structure from your mistakes, such as a washing machine overflow that ruins the neighbor's ceiling below.
Defining Haushaltsversicherung and Its Limits
The Haushaltsversicherung part of the bundle is what we typically think of as "renter's insurance." It covers the physical contents of your home against specific risks: fire, storm, water damage from burst pipes, and burglary. It is important to note that this covers your "movable" goods. The actual walls, windows, and roof of the building are covered by the landlord’s Gebäudeversicherung (Building Insurance), the costs of which are usually passed down to you through your monthly Betriebskosten (operating costs).
In an Austrian context, "theft" and "burglary" have very specific legal definitions. If you leave your front door unlocked and someone walks in and takes your laptop, your Money in Austria 2027: Banking, Payments, and Financial Setup guide will tell you that the insurance company will likely deny the claim because there was no "forcible entry." This is a classic example of why reading the policy details in Austria is so vital. Furthermore, if you live in a classic Vienna apartment, you need to understand the differences in Altbau vs Neubau: Differences in Rent, Charm, and Heating because older buildings often have higher risks of pipe bursts, which can impact your premiums.
Defining Privathaftpflicht and Why It Is the Hero
While the household portion covers your 500-euro TV, the Privathaftpflicht (Private Liability) portion covers your million-euro mistakes. This is arguably the most important insurance any resident of Austria can hold. In Austrian law, you are liable with all your current and future assets for damage you cause to a third party, whether that is bodily injury or property damage.
Imagine you are cycling through the Prater in Vienna and you accidentally collide with a pedestrian. If they are injured and cannot work, you could be looking at hundreds of thousands of euros in medical bills and lost wage compensation. This is where your Personal Liability Insurance (Privathaftpflicht): A Must-Have coverage steps in. Because it is bundled with your household insurance, you are protected not just inside your home, but usually anywhere in Europe (and often worldwide).
The liability portion of your policy also covers "passive legal protection." This means if someone makes an unjustified claim against you, your insurer will pay for the legal defense to fight it. This is different from a dedicated Legal Protection Insurance (Rechtsschutzversicherung) Overview, but it provides a basic level of security that every expat needs when navigating a foreign legal system for the first time.
Exceptions and Fine Print: When You Might Not Be Covered
Just because these two are bundled doesn't mean the coverage is universal or automatic. There are several "gotchas" in the Austrian insurance market that catch expats off guard. The most common one involves the distinction between "simple negligence" and "gross negligence" (Grobe Fahrlässigkeit).
Many modern Austrian policies include a "gross negligence" waiver, but the cheapest ones often do not. If you leave a candle burning while you go to the supermarket and your apartment catches fire, the insurance company might argue that this was gross negligence. Without that specific waiver in your policy, they can legally reduce your payout or refuse it entirely. When you are looking at your Checklist for Your First 30 Days in Austria, making sure your insurance includes Grobe Fahrlässigkeit should be a top priority.
The Dog and Pet Factor in Austria
If you are moving to Austria with a furry friend, you need to be extremely careful. While standard Privathaftpflicht usually covers small pets like cats, rabbits, or hamsters, it almost never covers dogs. In many Austrian provinces, including Vienna, you are legally required to have a separate or specific add-on for dog liability.
The Mandatory Liability Insurance for Dog Owners in Vienna rules are quite strict. If your dog causes a car accident or bites someone, your standard household insurance liability will likely point to the exclusion clause for dogs. You must ensure your policy explicitly lists your dog and meets the minimum coverage amounts required by your local Bezirkshauptmannschaft or Magistrate. I've seen many expats assume their bundle covered "everything in the house," only to be fined for not having the correct dog-specific liability certificate.
Coverage for Family and Roommates
Another area where the bundle can get complicated is who exactly is covered. A standard individual policy covers only the person named on the contract. If you are living with a partner or in a "WG" (flatshare), you need to make sure everyone’s name is either on the policy or that it is explicitly a "family" or "household" policy.
In a Finding a Shared Room (WG) via WG-Gesucht.de scenario, it is very common for one person to hold the main policy and the others to be "co-insured." However, don't just assume this is the case. If your roommate knocks over an expensive vase at a gallery, the insurer will check if they were officially part of the household policy. If they weren't, they are on their own. For families, the coverage usually extends to children until they finish their first degree or reach a certain age (often 25 or 27), provided they still live at home.
| Feature | Haushaltsversicherung (Household) | Privathaftpflicht (Liability) |
|---|---|---|
| Primary Focus | Your physical belongings (Furniture, Tech) | Damage you cause to other people/property |
| Location | Limited to the insured address | Usually worldwide or Europe-wide |
| Mandatory? | Often required by rental contracts | Not legally mandatory, but socially essential |
| Common Claim | Burglary, water damage from a pipe | Dropping a friend's phone, bike accident |
| Key Exclusion | Gross negligence (unless opted in) | Intentional damage, dog-related incidents |
Practical Steps for Expats in Austria
Navigating the insurance market requires a bit of strategy, especially when dealing with the Renting in Austria: MRG Laws, Leases, and Bestellerprinzip framework. Landlords have a lot of power in the Austrian market, and showing that you have a comprehensive insurance bundle makes you a much more attractive tenant.
When you apply for a flat, the landlord or the Hausverwaltung (property management) will almost always ask for a Versicherungsbestätigung (confirmation of insurance). You can usually get this within minutes from digital providers or traditional banks like Erste Bank or Raiffeisen. However, don't just sign the first thing they show you. Use a comparison tool to check if the liability limit is at least 5 million euros—anything less is considered risky in 2026.
Signing Up and Dealing with Landlords
When you sign a lease, especially Befristet (Fixed) vs Unbefristet (Unlimited) Lease Contracts, your insurance duration should ideally match your stay. Most Austrian insurance contracts used to be 10 years long by default, but you have a legal right to cancel them after the third year or if you move house. If you are leaving Austria entirely, you can cancel the policy immediately by providing your Abmeldebescheinigung (deregulation of address).
Landlords also often push for a specific amount of "Key Coverage" (Schlosstausch). In many Austrian Altbau buildings, the locks are part of a central system. If you lose your key, the management might have to change the locks for the entire building, which can cost thousands of euros. Make sure your bundled liability insurance includes "loss of private keys" with a high enough limit to cover an entire building's lock system.
Making a Claim Without the Stress
If the worst happens and you need to make a claim, the process in Austria is quite formal. You should always document the damage immediately with photos and videos. If it's a burglary, you must get a police report (Anzeige) before the insurance company will even talk to you. For liability claims, never admit fault at the scene of an accident. Simply exchange contact and insurance details and let your provider handle the communication.
In Austria, there is a strong culture of "Kulanz" (goodwill), but insurers are also very stickler-ish for deadlines. Most policies require you to report an incident within 48 to 72 hours. If you are struggling with the German terminology during a claim, you might want to look into Medical Translation Services: Interpreters for Hospital Visits as some of those services also offer help with general administrative translation, or better yet, choose an insurance provider that offers 24/7 English support.
Strategic Tips for Lowering Your Premiums
While insurance is a necessary expense, you shouldn't be overpaying. One of the easiest ways to lower your premium is to increase your Selbstbehalt (deductible). If you are willing to pay the first 150 or 250 euros of any claim yourself, your monthly cost will drop significantly. For most expats, this is a smart move because insurance should be for the "catastrophic" events, not for a broken 20-euro toaster.
Also, check if your employer or your union (Arbeiterkammer) offers any group discounts. Many large companies in Austria have partnerships with insurers like Wiener Städtische or Allianz. Finally, keep an eye on your Budgeting in Austria: Accurate Cost of Living Benchmarks to ensure your insurance costs stay within the 15-30 euro per month range, which is standard for a medium-sized apartment with good liability coverage in 2026.
Insurance Disclaimer
The information provided in this guide is for educational and informational purposes only and does not constitute professional financial, legal, or insurance advice. Insurance laws and policy terms in Austria can change frequently, and specific coverage depends entirely on the individual contract you sign. Always read the "Allgemeine Versicherungsbedingungen" (General Insurance Conditions) of your specific policy and consult with a licensed insurance advisor or broker to ensure your coverage meets your personal needs and legal obligations. No liability is accepted for actions taken based on this content.