Private Health Insurance: Hospital Class Coverage Upgrades
You’ve likely heard that Austria has one of the best healthcare systems in the world, but nobody mentions the reality of waking up in a six-bed ward. I remember feeling completely overwhelmed during my first surgery here, realizing that while my medical care was top-notch, my privacy was non-existent. This guide breaks down how private hospital class upgrades can transform your medical experience from functional to comfortable.
Understanding the Austrian Healthcare Landscape
Austria operates on a mandatory, universal healthcare system that is, admittedly, quite impressive compared to many other nations. However, for an expat who is used to a bit more personal space or a specific level of service, the "standard" can be a bit of a culture shock. When you move here, you are automatically enrolled in one of the public insurance providers, which provides the foundation for your care.
The Public Foundation: ÖGK and Friends
Almost every resident is covered by statutory social insurance. Depending on your employment, you might be under the ÖGK (for most employees), SVS (for the self-employed), or BVAEB (for public sector workers). This coverage is comprehensive, meaning you won’t be turned away for a life-saving surgery or a routine checkup. You’ll become very familiar with The Austrian e-card: Registration, Photo Rules, and Usage Guide as it is your golden ticket to these services.
The system is designed for efficiency and equity. In a public hospital, you receive "Allgemeine Klasse" (General Class) treatment. This means you are treated by whichever qualified doctor is on shift, and you are placed in a room with anywhere from three to six other patients. While the medical standards are identical across the board, the environment can feel a bit like a busy dormitory. For more details on how this works, check out Navigating Social Insurance: ÖGK, SVS, and BVAEB Overview.
Where Public Coverage Ends
The public system stops at "medical necessity." It does not cover the "nice-to-haves" that can make a traumatic health event significantly more bearable. For instance, if you want a specific surgeon who is a world-renowned expert in your condition, you might find they only operate privately or as a "Wahlarzt" (elective doctor). Without a private upgrade, you cannot simply choose your surgeon in a public hospital.
Furthermore, the public system does not guarantee peace and quiet. If you are recovering from a major procedure, sharing a room with five strangers—each with their own visitors, snoring habits, and late-night TV preferences—can hinder your recovery. This is where the Public vs Private Health Insurance in Austria Explained debate usually starts for most expats who have been here long enough to experience a hospital stay.
What is Hospital Class Coverage (Sonderklasse)?
When we talk about private upgrades in Austria, the term you will hear most often is "Sonderklasse" (Special Class). This is specifically an inpatient upgrade that changes your status within the hospital walls. It isn't just about a better pillow; it's a completely different administrative and clinical pathway.
The Zweibettzimmer vs Einbettzimmer Dream
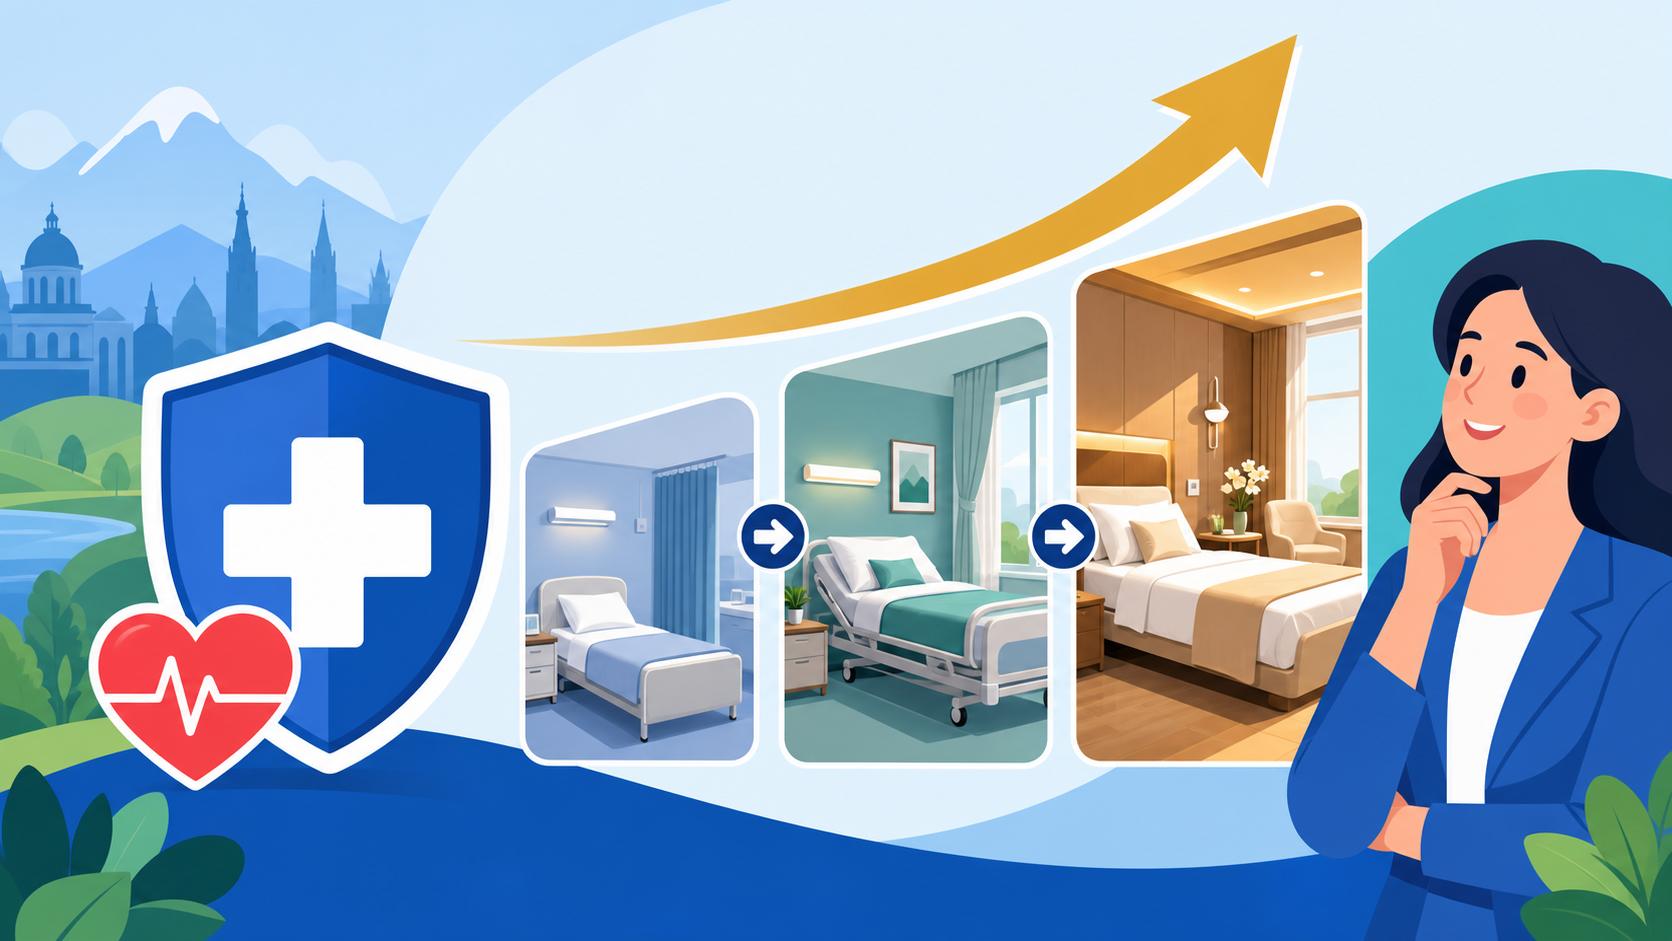
The most immediate benefit of Sonderklasse is room size. Most basic private hospital plans cover a "Zweibettzimmer" (double room). This limits your roommates to exactly one person. For many, this is the "sweet spot" of insurance—it’s significantly more private than a general ward but more affordable than the ultra-premium "Einbettzimmer" (single room) option.
Imagine you are in a hospital in Graz or Linz after a sudden illness. In a general ward, you might be next to the busy nurses' station with constant traffic. With a Sonderklasse upgrade, you’re usually moved to a separate wing or floor. These rooms often look more like hotel rooms, featuring private bathrooms, better meal options (sometimes even an a-la-carte menu), and more flexible visiting hours. If you're looking for care in the capital, my Vienna Healthcare Guide: Top Expat Clinics and Hospitals highlights some facilities where these private wings feel truly world-class.
Access to Senior Physicians: Chefarzt Treatment
The second, and perhaps more important, pillar of Sonderklasse is "freie Arztwahl" (free choice of doctor). In the public system, you are assigned a doctor. In the private system, you can choose the "Primarius" (Head of Department) or a "Chefarzt" (Senior Physician) to perform your surgery or manage your care.
This is a massive deal for complex procedures. If you’ve been seeing a specific specialist at their private practice—perhaps someone you found while Using a Wahlarzt (Private Doctor) and Claiming 80% Refunds—that doctor can usually follow you into the hospital to perform your surgery if you have the right private coverage. This continuity of care is incredibly reassuring. You aren't just a file being handed over; you are a patient being cared for by someone who knows your entire medical history.
Types of Private Upgrades Available
Not all private insurance is created equal. In Austria, you can "modularize" your coverage depending on your budget and what you fear most. Most expats don't need a full-blown private policy that covers everything from toothbrushes to therapy; instead, they focus on hospital upgrades.
Hospital-Only Coverage: Sonderklasse nach Unfall oder Krankheit
This is the most common entry point. It specifically covers your stay in the hospital if you are admitted due to an accident (Unfall) or an illness (Krankheit). These plans are designed to kick in only when you cross the threshold of a hospital. They won't help you with your daily visits to a GP, but they will ensure that if you ever need an operation, you're in the "Special Class."
There is a lighter version of this called "Sonderklasse nach Unfall." As the name suggests, it only upgrades your room and doctor choice if you are hospitalized due to an accident—like a skiing mishap in the Alps. Since illness is statistically more likely than a traumatic accident as we age, the "Unfall und Krankheit" version is the standard recommendation for long-term peace of mind. For those curious about the broader costs of care, Austria Healthcare System 2027: Complete Guide for Foreign Residents provides an excellent baseline.
Full Private Supplemental Plans
If you want the "all-inclusive" experience, you look at supplemental plans that include "Ambulante Heilbehandlung" (outpatient care). This covers your visits to private doctors (Wahlärzte), medications, glasses, and even alternative treatments like physiotherapy or massage.
When you have this level of coverage, you essentially bypass the public system’s waiting rooms entirely. You call a private specialist, get an appointment the next day, and the insurance company handles the bulk of the bill that the ÖGK doesn't cover. This is particularly helpful when Booking a Kassenarzt (Public Doctor): Wait Times and Tips proves too frustrating. It’s a luxury, certainly, but for many busy professionals, the time saved is worth the monthly premium.
Comparison: Public vs. Private Hospital Stay
| Feature | Public (Allgemeine Klasse) | Private (Sonderklasse) |
|---|---|---|
| Room Size | 3 to 6 beds per room | 1 or 2 beds per room |
| Doctor Choice | Assigned on-duty doctor | Free choice of Senior Physician |
| Waiting Times | Can be weeks/months for elective surgery | Significantly shorter; often immediate |
| Food & Amenities | Standard hospital catering | Expanded menu, private bathroom, TV/Wi-Fi |
| Continuity of Care | Different doctors per shift | Your specific specialist handles the case |
| Cost | Covered by social security | Monthly premium (usually €80 – €250+) |
The Financial Side: Premiums, Deductibles, and Taxes
Let’s talk money, because private insurance in Austria is an investment. Unlike some countries where private insurance is a replacement for public, here it is a top-up. You still pay your mandatory social security contributions—which you can see on your Lohnzettel Breakdown: Gross vs Net Salary Explained—and the private premium is an extra out-of-pocket expense.
How Premiums are Calculated
Your monthly premium is determined by three main factors: your age when you sign up, your current state of health, and the level of coverage you choose. Austria uses a "level premium" system. This means if you sign up at age 25, your premium stays relatively stable (inflation adjusted) for the rest of your life. If you wait until you are 50 to sign up, the cost will be significantly higher because you are entering a higher risk pool.
There is no "gender rating" in Austria anymore, so men and women pay the same for the same risk profile. However, smokers will almost always pay a surcharge. Some insurers also offer "Optionstarife" (Option Tariffs). This is a brilliant low-cost way for young expats to "lock in" their current health status and age for a few euros a month, giving them the right to upgrade to full Sonderklasse later without a new medical exam.
Tax Advantages and Deductibles
The Austrian tax office (Finanzamt) offers some relief here. While premiums themselves aren't always directly deductible as a standard expense for employees, they can sometimes be counted as "Extraordinary Expenses" if your total medical costs exceed a certain percentage of your income. For the self-employed, the rules are slightly different and often more favorable.
Many expats choose a "Selbstbehalt" (deductible) to lower their monthly costs. You might agree to pay the first €500 or €1,000 of a hospital stay yourself. If you are generally healthy and just want the insurance for a "worst-case scenario," opting for a higher deductible can slash your monthly premium by 20% or more. For more on managing these costs, see Deducting Extraordinary Medical Expenses (Wahlarzt Costs).
The Logistics of Switching and Using Your Coverage
Signing up for private insurance isn't as simple as clicking a button on a website. Because the insurers are taking on a long-term risk, they are quite meticulous during the onboarding process.
The Medical Exam and Pre-existing Conditions
When you apply for a hospital class upgrade, you will have to fill out a detailed health questionnaire. Be honest. If you omit a "minor" back problem that later requires surgery, the insurer can refuse to pay. In many cases, if you have a pre-existing condition, the insurer will either:
- Exclude that specific condition from coverage.
- Apply a "Risikozuschlag" (risk surcharge) to your premium.
- Decline the application entirely (though this is rare unless the condition is severe).
One pro-tip: Use your Annual Free Health Checkup (Gesundenuntersuchung) Details to get a clean bill of health before applying. Having a recent, official document showing you're in good shape can sometimes smoothen the underwriting process.
The Waiting Period (Wartezeit)
Most policies have a "Wartezeit" (waiting period). Usually, you cannot use the private hospital benefits for the first three months of the policy. For maternity-related hospital stays, the waiting period is often nine months to a year. This prevents people from signing up only when they know they have an impending medical need. The only exception is usually accidents; if you sign your papers today and have a car crash tomorrow, the "Unfall" portion of the coverage usually kicks in immediately.
Is it Worth it? A Realistic Expat Assessment
This is the question I get asked most often over coffee in the 7th District. The answer depends entirely on your lifestyle and your tolerance for the "communal" aspects of Austrian life.
Comparing Costs for Singles vs. Families
For a single expat in their late 20s or early 30s, a basic Sonderklasse plan can be surprisingly affordable—often less than the cost of a few nice dinners out a month. As you start adding family members, the costs climb. However, children are very cheap to insure. Adding a child to a private plan is often a fraction of the adult cost, and it ensures they get the best pediatric specialists in the country.
If you are a freelancer, the Healthcare Costs: Kassenarzt vs Wahlarzt Differences Explained might steer you toward private insurance more quickly. Since your income depends on your ability to work, getting into surgery faster and recovering in a private room can be seen as a business continuity expense.
Alternatives and Hybrid Strategies
You don't always need the "Gold Standard." Some people choose to stay with public insurance but "self-insure" for smaller things. They might pay out of pocket for a private doctor visit once or twice a year but rely on the public system for major surgeries.
The danger with this strategy is the "Sonderklasse" cost. A private hospital stay without insurance can cost €1,000 to €2,000 per day. A week-long stay for a major procedure could easily clear out your savings. Private insurance isn't just about the luxury of a private room; it's about capping your financial risk against those massive hospital bills.
Final Thoughts for the New Arrival
Austria's medical system will take care of you regardless of your insurance status, but private "Hospital Class" coverage dictates how you are taken care of. It’s about dignity, privacy, and the ability to choose the expert you trust with your life. If you plan on staying in Austria long-term, my advice is to look into these options while you are young and healthy. The "entry price" you lock in today will be a gift to your future self when you eventually need that extra bit of comfort and care.
Disclaimer
This guide is provided for informational purposes only and does not constitute financial, legal, or medical advice. Insurance laws and premium rates in Austria are subject to change. Always consult with a licensed insurance broker or legal professional before signing any contracts to ensure the coverage meets your specific needs.