How SEPA Instant Transfers Work Between European Banks
Waiting for a bank transfer to clear while your landlord breathes down your neck is a rite of passage for every newcomer in Austria. I remember the panic of my first month in Vienna, staring at a screen on a Friday afternoon, praying my deposit would arrive before the weekend void swallowed my transaction. This guide explains how SEPA Instant transfers eliminate that stress by moving money across Europe in seconds.
The Evolution of Banking in Austria From Wait and See to SEPA Instant
For years, the Austrian banking system operated on a schedule that felt slightly disconnected from the digital age. If you sent money on a Friday evening, you could practically guarantee it wouldn't be seen by the recipient until Tuesday morning. This "banking dead zone" has long been a source of frustration for expats trying to navigate Money in Austria 2027: Banking, Payments, and Financial Setup. We are used to instant gratification in our digital lives, yet our money often felt like it was traveling by stagecoach across the Alps.
The introduction of the SEPA Instant Credit Transfer (SCT Inst) scheme changed the landscape entirely. Unlike the traditional SEPA Credit Transfer, which relies on "batches" processed at specific times during the business day, the instant version works 24/7, 365 days a year. This means Christmas Day, Easter Sunday, or a random Tuesday at 3:00 AM are all fair game for moving funds. When you are Opening an Austrian Bank Account: Requirements and Top Banks, understanding whether your chosen institution prioritizes this technology is just as important as knowing their monthly maintenance fees.
We are seeing a massive shift. The European Union has moved to mandate that all banks offering standard SEPA transfers must also offer the instant version at no extra cost. For those of us who have lived here long enough to remember paying five euros just to "rush" a payment, this is a revolutionary change in the financial ecosystem. It levels the playing field for traditional institutions and the newer fintechs that many expats prefer.
What Exactly is a SEPA Instant Transfer
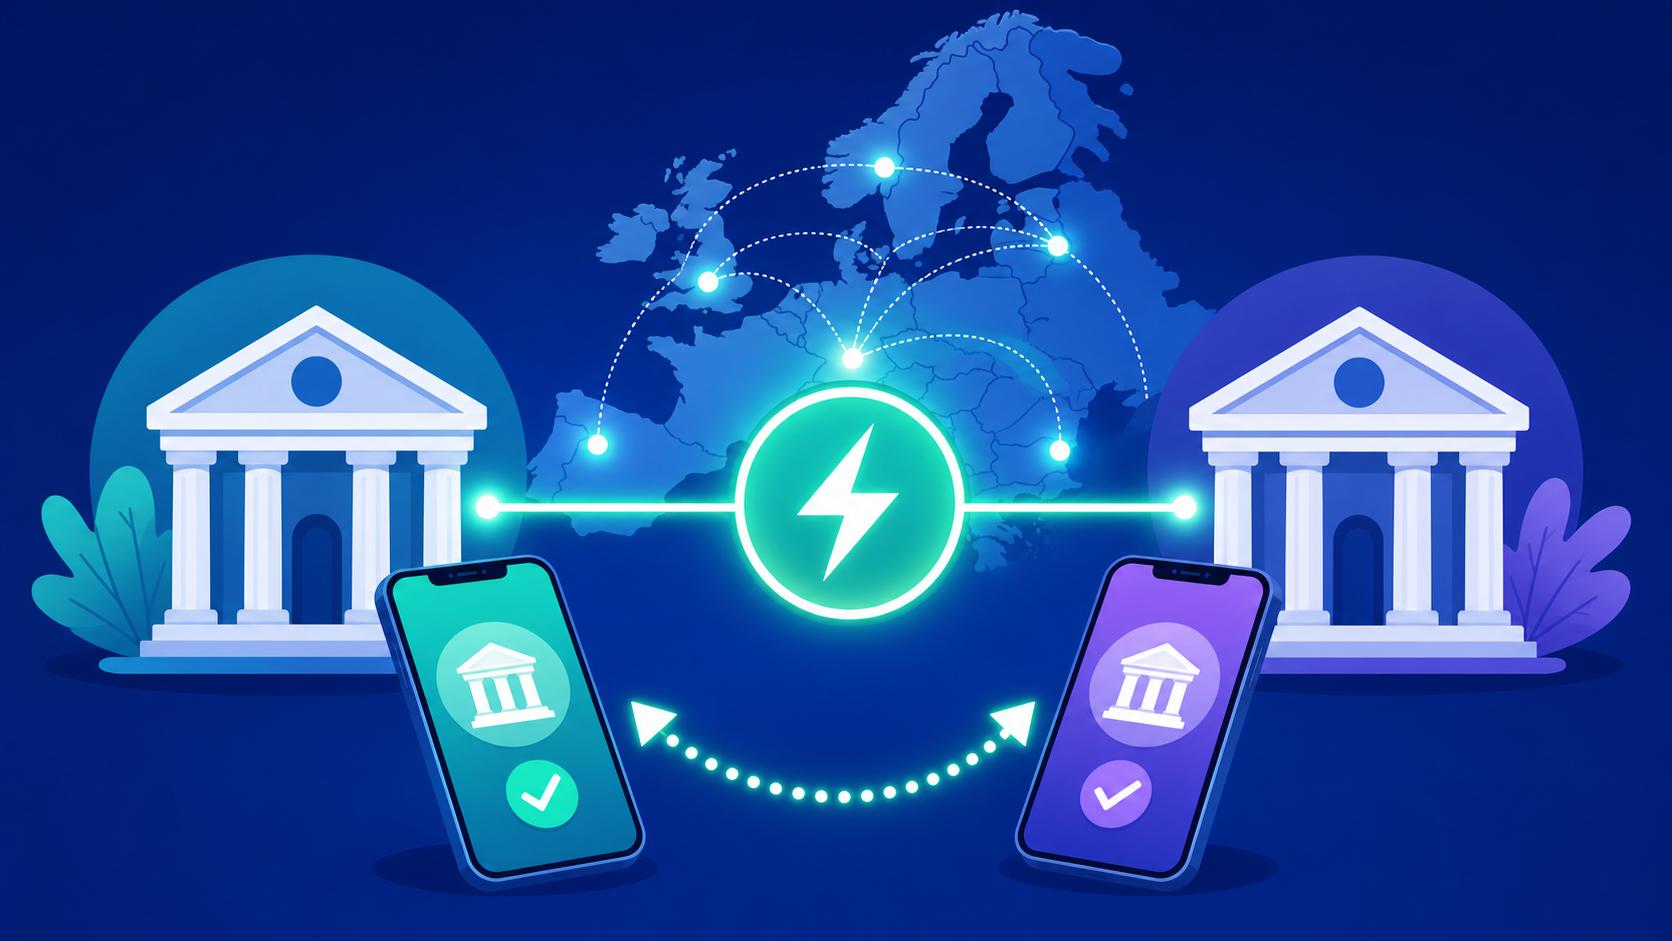
To understand why this matters, we have to look under the hood of the Single Euro Payments Area (SEPA). Traditional transfers go through a clearinghouse where transactions are gathered, sorted, and then moved in bulk. It is efficient for the banks but slow for the user. SEPA Instant, however, operates on a "real-time" settlement basis. The moment you hit send, the originating bank communicates with the receiving bank via a clearing service like TIPS (TARGET Instant Payment Settlement) or RT1.
The technical requirement for a transfer to be classified as "Instant" is that the funds must be available in the recipient's account within ten seconds. In reality, across most European borders, it usually takes less than three. This isn't just about the numbers on a screen; it’s about the legal finality of the payment. Once those ten seconds have passed, the money belongs to the recipient, and the transaction cannot be revoked by the sender.
This speed is particularly vital for expats who maintain financial footprints in multiple countries. If you are Comparing Erste Bank, Raiffeisen, and Bank Austria, you will find that their integration with these real-time rails varies. Some have been "receiver-only" for years, meaning they could take your instant money but wouldn't let you send it out instantly without a hefty fee. By mid-2026, these barriers have largely crumbled due to regulatory pressure, making cross-border life significantly easier.
Austrian Banks and SEPA Instant Availability
Austria has a dense banking network, but it can be surprisingly conservative. You have the large "Big Three"—Erste Bank, Raiffeisen, and Bank Austria—alongside a sea of smaller regional Volksbanken and Sparkassen. Historically, Raiffeisen and Erste were early adopters of the technology, while others lagged behind. If you are using Neobanks in Austria: Using N26 or Revolut for Salaries, you’ve likely been enjoying instant transfers for years, as these digital-first banks built their entire infrastructure around SCT Inst.
When you log into your George (Erste Bank’s app) or your Raiffeisen ELBA, you will often see a small toggle or a checkbox labeled "Instant" or "Echtzeit-Überweisung." In the past, clicking this box might have triggered a warning about a fee, often ranging from €0.50 to €2.00. However, as we move forward, most accounts have integrated this as the default setting. It is always worth checking your Bank Fees: Understanding Account Maintenance and ATM Charges to ensure you aren't being surreptitiously charged for a service that is now becoming a standard European right.
One quirk of the Austrian system is the "limit" culture. Even if your bank supports SEPA Instant, they may place a daily cap on how much you can send this way—often €15,000 or €100,000 depending on the scheme's current rules. If you are trying to pay a large car deposit or a down payment on a flat, you might find the "Instant" option greyed out if the amount exceeds these thresholds. In those cases, you’re back to the old-fashioned one-business-day wait.
| Feature | Standard SEPA (SCT) | SEPA Instant (SCT Inst) |
|---|---|---|
| Processing Time | 1 Business Day | Under 10 Seconds |
| Availability | Business Hours Only | 24/7/365 |
| Max Amount | Virtually Unlimited | Usually €100,000 |
| Geographic Reach | 36 SEPA Countries | Participating Banks in SEPA |
| Settlement | Batched | Real-time |
| Cost (2026) | Usually Free | Must match Standard (Free) |
Practical Scenarios When You Will Need SEPA Instant in Austria
The most common "fire" expats need to put out involves SEPA Transfers, Dauerauftrag, and Paying Rent. In Austria, being late with rent is a serious matter. Many rental contracts state that the money must be in the landlord's account by the 5th of the month. If the 5th is a Sunday, and you forget to send the money on Thursday, a standard transfer won't arrive until Monday the 6th. An instant transfer ensures that even if you remember at 11:00 PM on Sunday night, the money is there before the clock strikes midnight.
Another scenario is buying used items on platforms like Willhaben. While cash is still king in many parts of Austria, the rise of instant transfers has made "Willhaben Pay" or direct bank transfers at the point of exchange much more popular. Imagine going to pick up a sofa in a different district; you can show the seller the "Sent" screen, and they can check their own app to see the balance update immediately. This removes the "trust" barrier that often plagues private sales.
Then there is the issue of Lohnzettel Breakdown: Gross vs Net Salary Explained. Sometimes your employer might be late with a payment, or there’s a discrepancy in your 13th or 14th salary. If they use SEPA Instant to correct an error, you don't have to wait days for the funds to hit your account so you can pay your bills. This immediate liquidity is a massive stress-reducer for anyone living on a tight budget in an expensive city like Vienna or Salzburg.
Step-by-Step Sending an Instant Transfer from an Austrian Account
Sending an instant transfer isn't much different from a regular one, but there are a few nuances to look out for. First, you need the recipient's IBAN. The banking system automatically checks the IBAN to see if the receiving bank is part of the SCT Inst scheme. If it is, the "Instant" option will usually become available.
- Log in to your Online Banking or App: Whether it's George, ELBA, or a neobank app, navigate to the "Transfer" (Überweisung) section.
- Enter Recipient Details: Type in the name and IBAN. The system should recognize the bank instantly.
- Enter the Amount: Be mindful of your daily limits. If the amount is very high, the "Instant" option might disappear.
- Select "Instant" (Echtzeit): If it isn't already selected by default, look for the toggle. Most apps prioritize this.
- Review and Sign: Use your sIdentity app, SMS tan, or Using ID Austria for E-Banking and FinanzOnline Access to authorize the payment.
- Confirmation: You will receive a notification almost immediately that the funds have reached the other side.
It is important to note that if you are Closing Bank Accounts and Contracts When Leaving Austria, you should use instant transfers to move your remaining balance to your new international account. This ensures the account is truly empty before you sign the closure paperwork, preventing those annoying "residual interest" cents from keeping the account open and racking up fees.
Limits Security and Troubleshooting
While SEPA Instant is incredibly fast, it isn't magic. There are times when it might fail. The most common reason is that the receiving bank simply doesn't support it yet. While the EU has mandated support, some very small, rural banks or specialized institutions might still be in the process of a rollout. If the "Instant" checkbox is greyed out, that’s usually why.
Security is another concern. Because the money moves so fast, it is a favorite tool for scammers. Once you send the money and those ten seconds pass, it is gone. There is no "stop payment" button. This is why you must be absolutely certain of the recipient's identity. If you're paying a deposit for a flat you haven't seen, be extremely cautious. Many expats have fallen for rental scams where they are pressured to send an instant transfer to "reserve" a flat, only to find the "landlord" vanishes.
If a transfer is marked as "Pending" or "Failed," don't panic. Sometimes the clearinghouses (TIPS/RT1) experience technical hiccups. If the transfer doesn't clear within the 10-second window, the system is designed to "time out" and return the funds to your account. However, in rare cases, it can get stuck in a "pending" state for an hour or two while the banks communicate. If this happens, wait for the official notification before trying to send the money a second time, or you might end up paying twice.
Dealing with the Meldezettel and Administrative Fees
Even the government is getting on board. While many administrative offices in Austria still prefer a "Zahlschein" (payment slip) or a debit card payment in person, more departments are accepting bank transfers for things like visa fees or residency permit renewals. If you are in the middle of The Meldezettel Process: Registering Your Address Legally and need to pay a small fee for a duplicate or a specific confirmation, an instant transfer can speed up the bureaucratic machinery.
In the past, you might have had to wait for the MA 35 or your local Bezirkshauptmannschaft to "see" your payment before they would issue a document. With the transparency of instant banking, providing a PDF confirmation of an instant transfer is increasingly accepted as proof of payment on the spot. This can save you a second trip to a government office, which, as any expat knows, is worth its weight in gold.
Disclaimer
This guide is for informational purposes only and does not constitute financial or legal advice. Banking regulations, fees, and the availability of SEPA Instant features can change. Always verify the specific terms and conditions with your individual banking provider in Austria. External links provided are for reference and may be updated by the respective authorities or organizations.